EMI changes when you pay; it does not automatically reduce what you pay. A bank discount, standard EMI and “no-cost EMI” are different arrangements. Compare the complete payable amount, lender schedule and lost alternatives before selecting instalments.
Standard EMI
With standard EMI, the lender splits the financed amount across a tenure and charges interest under its terms. The monthly amount can look manageable while the total repayment exceeds the cash price. Review the annual rate, tenure and any processing or foreclosure conditions.
What no-cost EMI generally means
In a no-cost structure, the merchant or partner may offset the stated interest through an upfront discount or another adjustment. Taxes on interest, processing fees or card charges may still apply. The exact schedule from the lender is more important than the label.
Bank discount versus EMI benefit
An instant bank discount lowers the transaction amount when an eligible card and purchase meet the terms. An EMI offer may instead depend on a particular tenure or provide a later benefit. Some promotions cannot be combined, so compare cash price, discounted card price and total EMI repayment separately.
Costs shoppers often miss
- processing or conversion fees;
- taxes applied to interest or fees;
- a lost cash, coupon or card discount;
- late-payment and over-limit charges;
- foreclosure or cancellation treatment;
- a refund that does not immediately close the EMI plan.
A simple comparison method
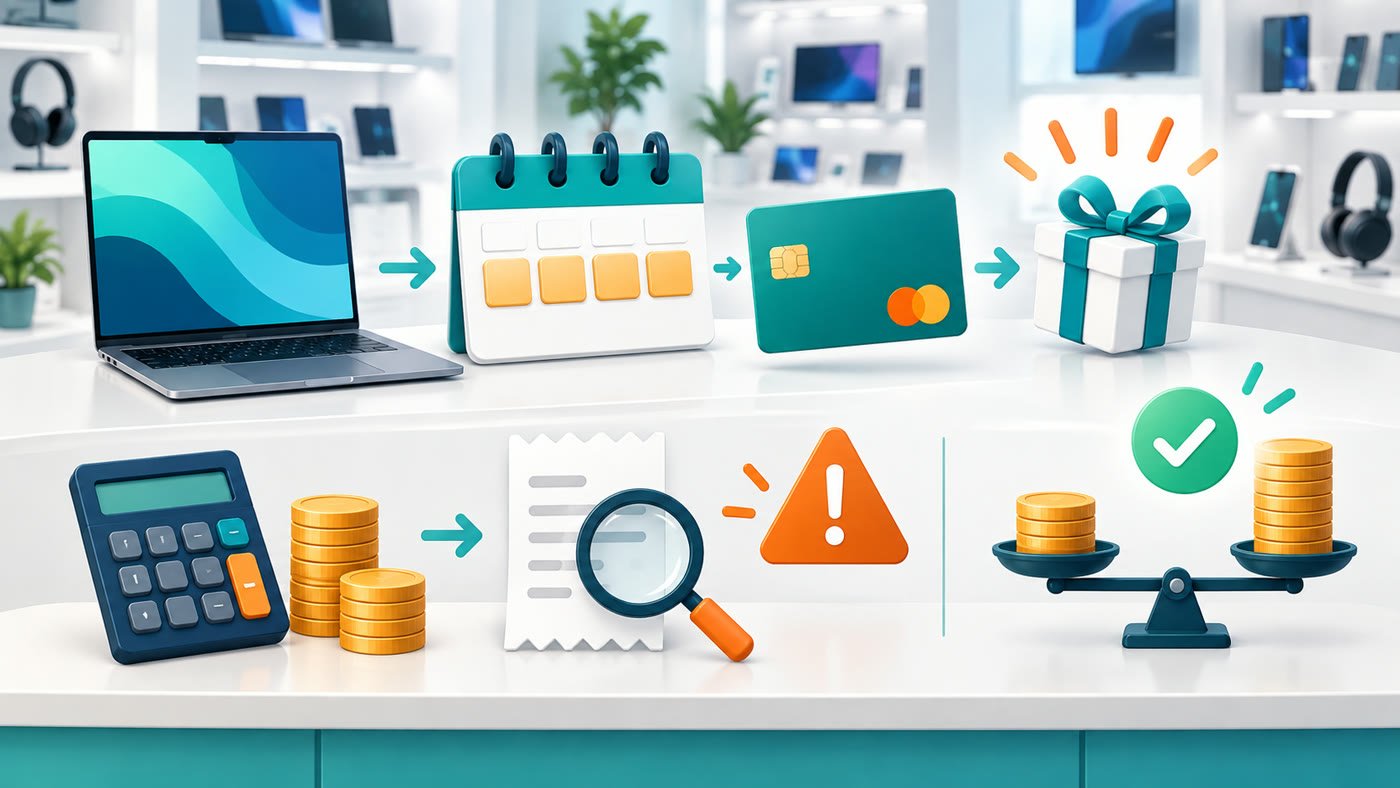
- Record the final non-EMI checkout price.
- Record every EMI instalment and upfront charge.
- Add taxes, processing and card fees shown by the lender.
- Subtract only benefits that are confirmed and realistically creditable.
- Compare the total, not only the monthly instalment.
Eligibility and credit considerations
Card type, issuer, transaction value, product and tenure can control eligibility. EMI uses a credit facility and missed payments can have financial consequences. Do not choose a longer tenure solely to make an unnecessary purchase appear affordable.
Returns and cancellations
A retailer refund and an EMI cancellation can move on different timelines. Ask how interest, fees and prepayments are handled, then monitor both the merchant and lender records until the adjustment is complete.
For merchant-specific context, see Samsung India, boAt and Wakefit. You can also browse Electronics & Appliances.
This is general shopping information, not financial advice. Confirm the current schedule and charges with the lender before accepting an EMI plan.